Mexico’s office real estate market continues to adapt to an economic environment characterized by restrictive financial conditions and rising operating costs. Throughout 2026, the cost of capital has constrained some corporate activity, while geopolitical tensions and increased fuel costs have also impacted companies' expansion plans. Against this backdrop, demand has become more selective, favoring higher-quality spaces that offer greater flexibility to meet operational needs.
As of the end of September 2026, the national office inventory—covering the eight markets monitored by Solili—reached 18 million square meters, a 2.2% increase year-over-year. Inventory growth remains moderate, consistent with the reduced development activity that has characterized the market since the pandemic.

The supply of office space continues to shrink. In September 2026, vacant space totaled 2.6 million square meters—a 6% decrease from the previous year and 13% below the figure for September 2024. Over the past two years, vacancy has dropped by more than 400,000 square meters, confirming a downward trend. This level of availability is reflected in the national vacancy rate, which closed the month at 14.7%.
Average asking prices are showing moderate movement. In September 2026, the national average price reached $20.75 per square meter per month, up 2% from September 2025 and 4% higher than in September 2024. After remaining relatively stable during the first few months of 2026, prices resumed an upward trajectory in June, reaching their highest level in two years by September.

Office deliveries in Mexico remained at a moderate level during September 2026. Only 4,000 square meters were added to the national inventory that month. However, total deliveries from January to September 2026 reached 198,000 square meters—more than double the figure recorded during the same period in 2025. Meanwhile, construction starts totaled 700 square meters in September. For the January–September period, they totaled 178,000 square meters, compared to 36,000 during the same period in 2025.
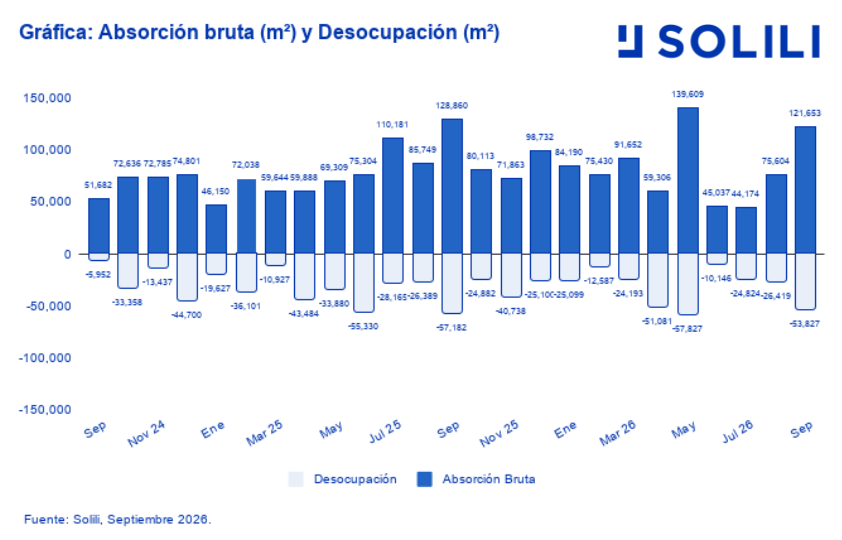
Gross office absorption in the country totaled 122,000 square meters in September 2026; this was 6% lower than in September 2025 but more than double the level recorded in September 2024. Year-to-date demand has reached over 737,000 square meters—5% higher than in the same period of 2025—remaining above the levels observed a year earlier.

Demand for office space across the eight major corporate markets continues to shift toward higher-quality premises, particularly among domestic and international companies prioritizing established locations, infrastructure, and conditions suited to their operational needs. At the same time, flexible formats and the integration of services, amenities, and mixed-use elements continue to reshape user requirements and the way corporate spaces are occupied.
As 2026 draws to a close, the office market is showing signs of better balance, although corporate decision-making remains cautious. Market performance will be driven by the evolving geopolitical and financial landscape, as well as domestic economic conditions. Reduced space availability and stable rents are creating a more favorable environment for recovery, while the manufacturing, logistics, and services sectors continue to drive demand.
Stay up to date with the most important news to the real estate
Subscribe Solili Newsletter