The office real estate market in Mexico continues to adapt to an economic environment in which companies remain cautious regarding their investment decisions. Financial conditions, operating costs, and uncertainty surrounding the international economic outlook continue to influence corporate strategies. In this context, demand remains selective, favoring spaces that offer superior locations, infrastructure, and operational flexibility. Meanwhile, rental prices remained stable in October, following an upward trend observed over the previous months.
The amount of vacant office space across the country’s eight major corporate markets saw a slight increase in October 2026, reaching 2.67 million square meters—approximately 1% more than in September. Nevertheless, on an annual basis, there remains a 5% reduction compared to October 2025. When compared to October 2024, available space has decreased by nearly 12%, confirming that—despite the monthly uptick—the overall supply has followed a downward trajectory over the past two years.

Meanwhile, asking rents continue to trend upward. In October 2026, the national average price stood at 20.77 USD per square meter per month—3% higher than the level recorded a year earlier and 4% higher than in October 2024. After remaining stable for much of 2025 and the first few months of 2026, prices began to show consistent increases starting in June, reaching their highest levels in September and October 2026. In the latter month, prices remained unchanged from September, following the increases recorded since the middle of the year. No new deliveries were added in October 2026. However, the cumulative total from January to October reached 198,000 square meters—an 84% increase compared to the same period in 2025. Meanwhile, construction starts totaled 14,500 square meters in October, bringing the year-to-date figure to 193,000 square meters—more than triple the volume seen in 2025. This reflects increased activity in the launch of new projects, despite the prevailing caution within the corporate real estate segment.

The amount of office space under construction has remained stable over the last few months. As of the end of October 2026, it stood at approximately one million square meters—down from the levels exceeding 1.2 million square meters recorded during 2024 and 2025. Although construction starts indicate higher activity, the overall volume of projects currently underway remains moderate, with future supply concentrated primarily in larger-scale corporate markets.
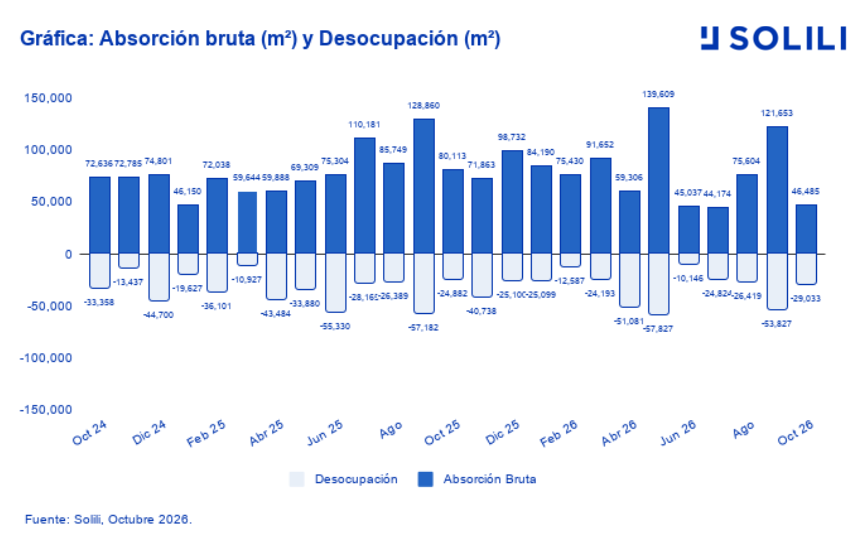
On the demand side, national gross office absorption declined in October 2026, reaching 46,000 square meters—42% less than in the same month of 2025 and 36% below the figure for October 2024. For the period from January to October 2026, total demand reached just over 780,000 square meters, remaining at levels similar to those reported during the same period the previous year. In contrast, the amount of office space vacated reached 29,000 square meters in October—a 46% monthly decrease, though 17% higher than the volume recorded in October 2025. From January to October of this year, the total vacated space amounted to approximately 315,000 square meters, a 6% decrease compared to the same period the previous year.

As we approach the end of 2026, the office market maintains a better balance compared to the vacancy levels seen in previous years, with demand remaining stable. Companies' preference for established locations, higher-quality spaces, and flexible formats will continue to influence occupancy decisions. Meanwhile, the performance of new projects will depend on the market's ability to sustain demand and on the financial conditions faced by developers.
Stay up to date with the most important news to the real estate
Subscribe Solili Newsletter