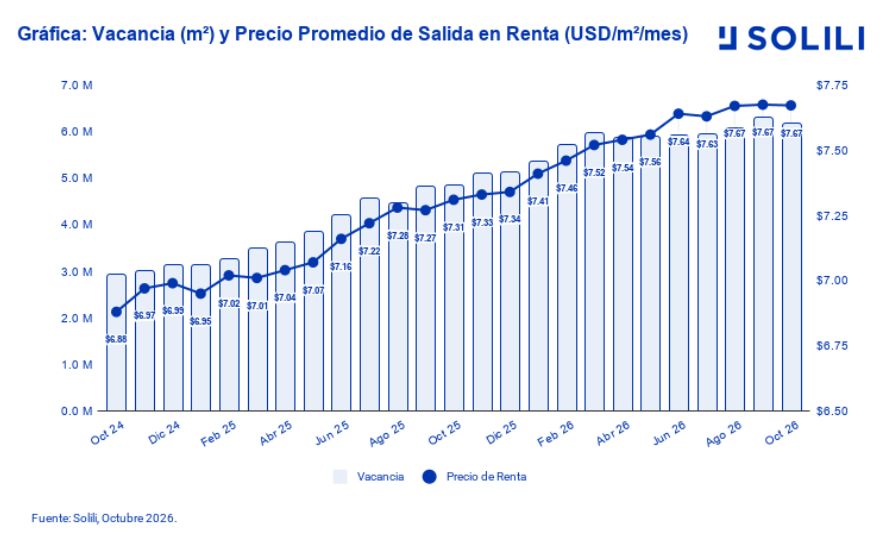
The national industrial real estate market continues to go through an adjustment period, characterized by still-elevated vacancy levels, which declined slightly month over month in October, and more moderate construction activity. Given this outlook, developers are taking a more selective stance toward launching new projects, while demand remains solid and rental prices show stability, reflecting a market seeking to balance existing supply with companies’ occupancy needs.
Rising vacancy continues to be one of the main challenges for the national industrial market. In October 2026, vacant space reached 6.2 million square meters, approximately 29% more than a year earlier and more than double the level recorded in October 2024. However, after five consecutive months of increases, vacancy showed a slight monthly decline of approximately 100 thousand square meters in October 2026.

Although the market still reports elevated vacancy levels, asking prices for industrial properties have remained stable. In October 2026, the national average price stood at $7.67 per square meter per month, 5% above the level recorded a year earlier and nearly 12% higher than in October 2024. However, over the last three months the indicator has remained unchanged, reflecting a pause in the increases seen since the beginning of the year. Given the higher vacancy levels, maintaining competitive rental pricing remains important for developers.
During October 2026, new industrial supply reached 388 thousand square meters, 15% below the same month of 2025, although deliveries continue to add space to the national inventory. For the year-to-date period from January to October, new additions totaled 3.9 million square meters, a 28% decrease compared to the same period of the previous year. This moderation is even more pronounced in construction starts, which in October totaled 107 thousand square meters, compared to 615 thousand square meters in the same month of 2025.

Between January and October 2026, construction starts accumulated 2.6 million square meters, 39% less than in the same period of the previous year. The decline reflects greater selectivity in project development, particularly in an environment where available space continues to grow and companies’ investment decisions maintain a cautious pace.
Industrial construction activity nationwide also continues to follow a downward trajectory. At the close of October 2026, 3.1 million square meters were under construction, 31% less than a year earlier and nearly 48% below October 2024. Over the past two years, the volume of projects under development has fallen by approximately 2.8 million square meters, reflecting the adjustment that construction activity has undergone.

On the demand side, gross absorption registered 464 thousand square meters during October 2026, 7% less than in the same month of the previous year. However, the year-to-date result remains favorable, as 4.5 million square meters were occupied between January and October, representing 7% growth compared to the same period of 2025.
As for move-outs, October saw movements of approximately 120 thousand square meters, above the 73 thousand square meters recorded in the same month of 2025, although below the September 2026 figure. In the cumulative first ten months of the year, vacated space totaled around 1.7 million square meters, 8% more than in the comparable period of the previous year.

Toward the end of 2026, the market will face the challenge of placing available space in an environment of still-cautious investment decisions. The reduction in new projects could help moderate supply growth in the medium term, although accumulated vacancy will remain a relevant factor for developers. The evolution of the USMCA and companies’ expansion decisions will be decisive for demand performance in the final months of the year.
Stay up to date with the most important news to the real estate
Subscribe Solili Newsletter